DEMAND SPUTTERS, VACANCY GAINS, SUBLEASES HIT RECORD
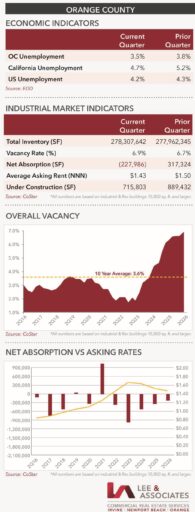
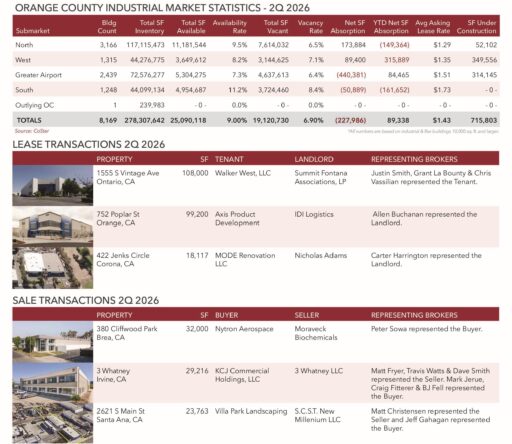
After two quarters of positive net absorption, tenant demand fell into the red in the second quarter and has been negative for 12 of the last 14 quarters. Also, space available for sublease hit a record, the pace of development has cooled and the overall vacancy rate is the highest in 15 years.
Countywide second-quarter growth was negative 227,986 SF with the Airport and South County markets reporting 4491,280 SF of tenant contraction.
Since early 2023, the combination of nearly 10 million SF of reduced user demand and a 5.1-million-SF increase in inventory has pushed up the available space total from 11.2 million SF to 25 million SF. The countywide vacancy rate rose from a record low of 1.8% to 6.9%. The nationwide average is 7.5%.
The second-quarter volume of sublease space grew to 4.6 million in Q2, well beyond historical norms. The increase was, in part, due to a short-term listing for 1 million SF of second-hand space in Buena Park.
Because of the slowing market and shortage of land, the amount of space under construction has fallen to its lowest level in five years. Currently, there are seven buildings underway totaling 715,803 SF – ranging from 25,000 SF to 150,000 SF – compared to 23 buildings in the pipeline a year ago. The largest building underway totals 192,894 SF and is in the Goodman Commerce Center in Cypress.
Market asking rents are down 12% from their peak two years ago. With increased concessions, effective rents have declined slightly further.
Free rent and other concessions are common. It also takes longer to land a user while tenants with large requirements have grown scarcer. For example, asking rent for a state-of-the-art logistics building at 2872 E. La Palma Ave., Anaheim – vacant since its 2023 completion – has been reduced more than half.
Several of the buildings completed in the past year and nearly all speculative projects underway remain available for lease, a further reflection of the recent softening in demand across the county ranging from about 25,000 SF to about 150,000 SF.
Small buildings are landing tenants in about four months compared to more than nine months for buildings larger than 100,000 SF.
The largest lease of Q2 was for 223,406 SF in Huntington Beach to Harbor Distribution for 66 months and starting at $1.15 per SF.
Investment activity in Orange County’s industrial market remains constrained. Fewer than 50 buildings traded in 2026 Q1, with deal flow near all-time lows and limited sales volume. Activity remained subdued in Q2, reflecting continued investor caution in large port markets.
The largest sale in Q2 was the $107 million acquisition by investor Kurv Industrial for a leased-up 348,230-SF building in the Irvine Spectrum.
MARKET FORECAST
The war with Iran, rising fuel costs, persistent inflation and interest rates were seen by local business leaders as the biggest challenges facing area companies, according to a Q2 survey by economists at Cal State Fullerton. Other issues included housing, government deficits, AI and stock market volatility. Tariffs were no longer a great concern, the survey said.