TENANT DEMAND SURGES; FIRMING FOR SLIDING RENTS
Strong countywide demand for industrial space returned in the third quarter with the most tenant growth for any three-month period since late 2022. A long slide in overall rents also came to a halt.
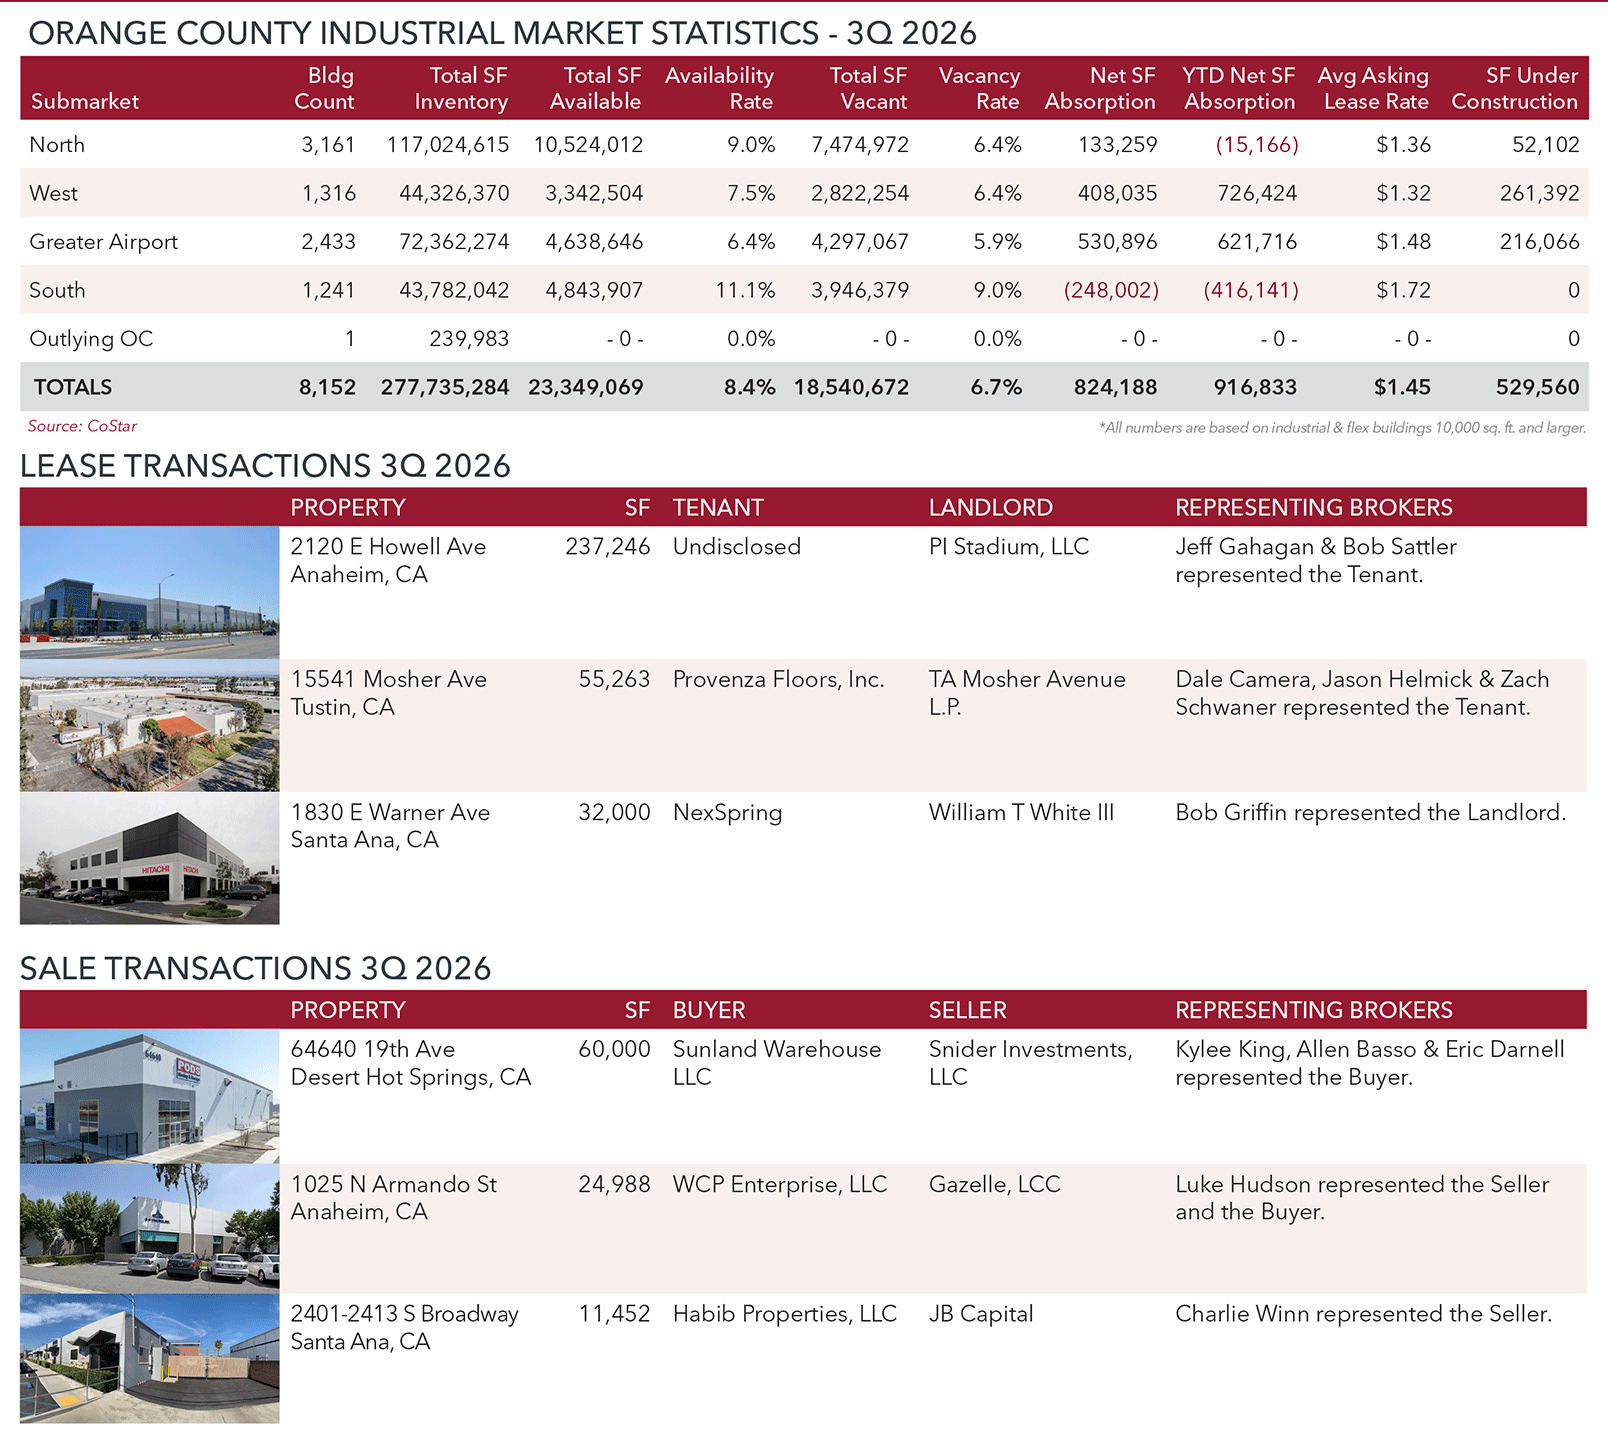
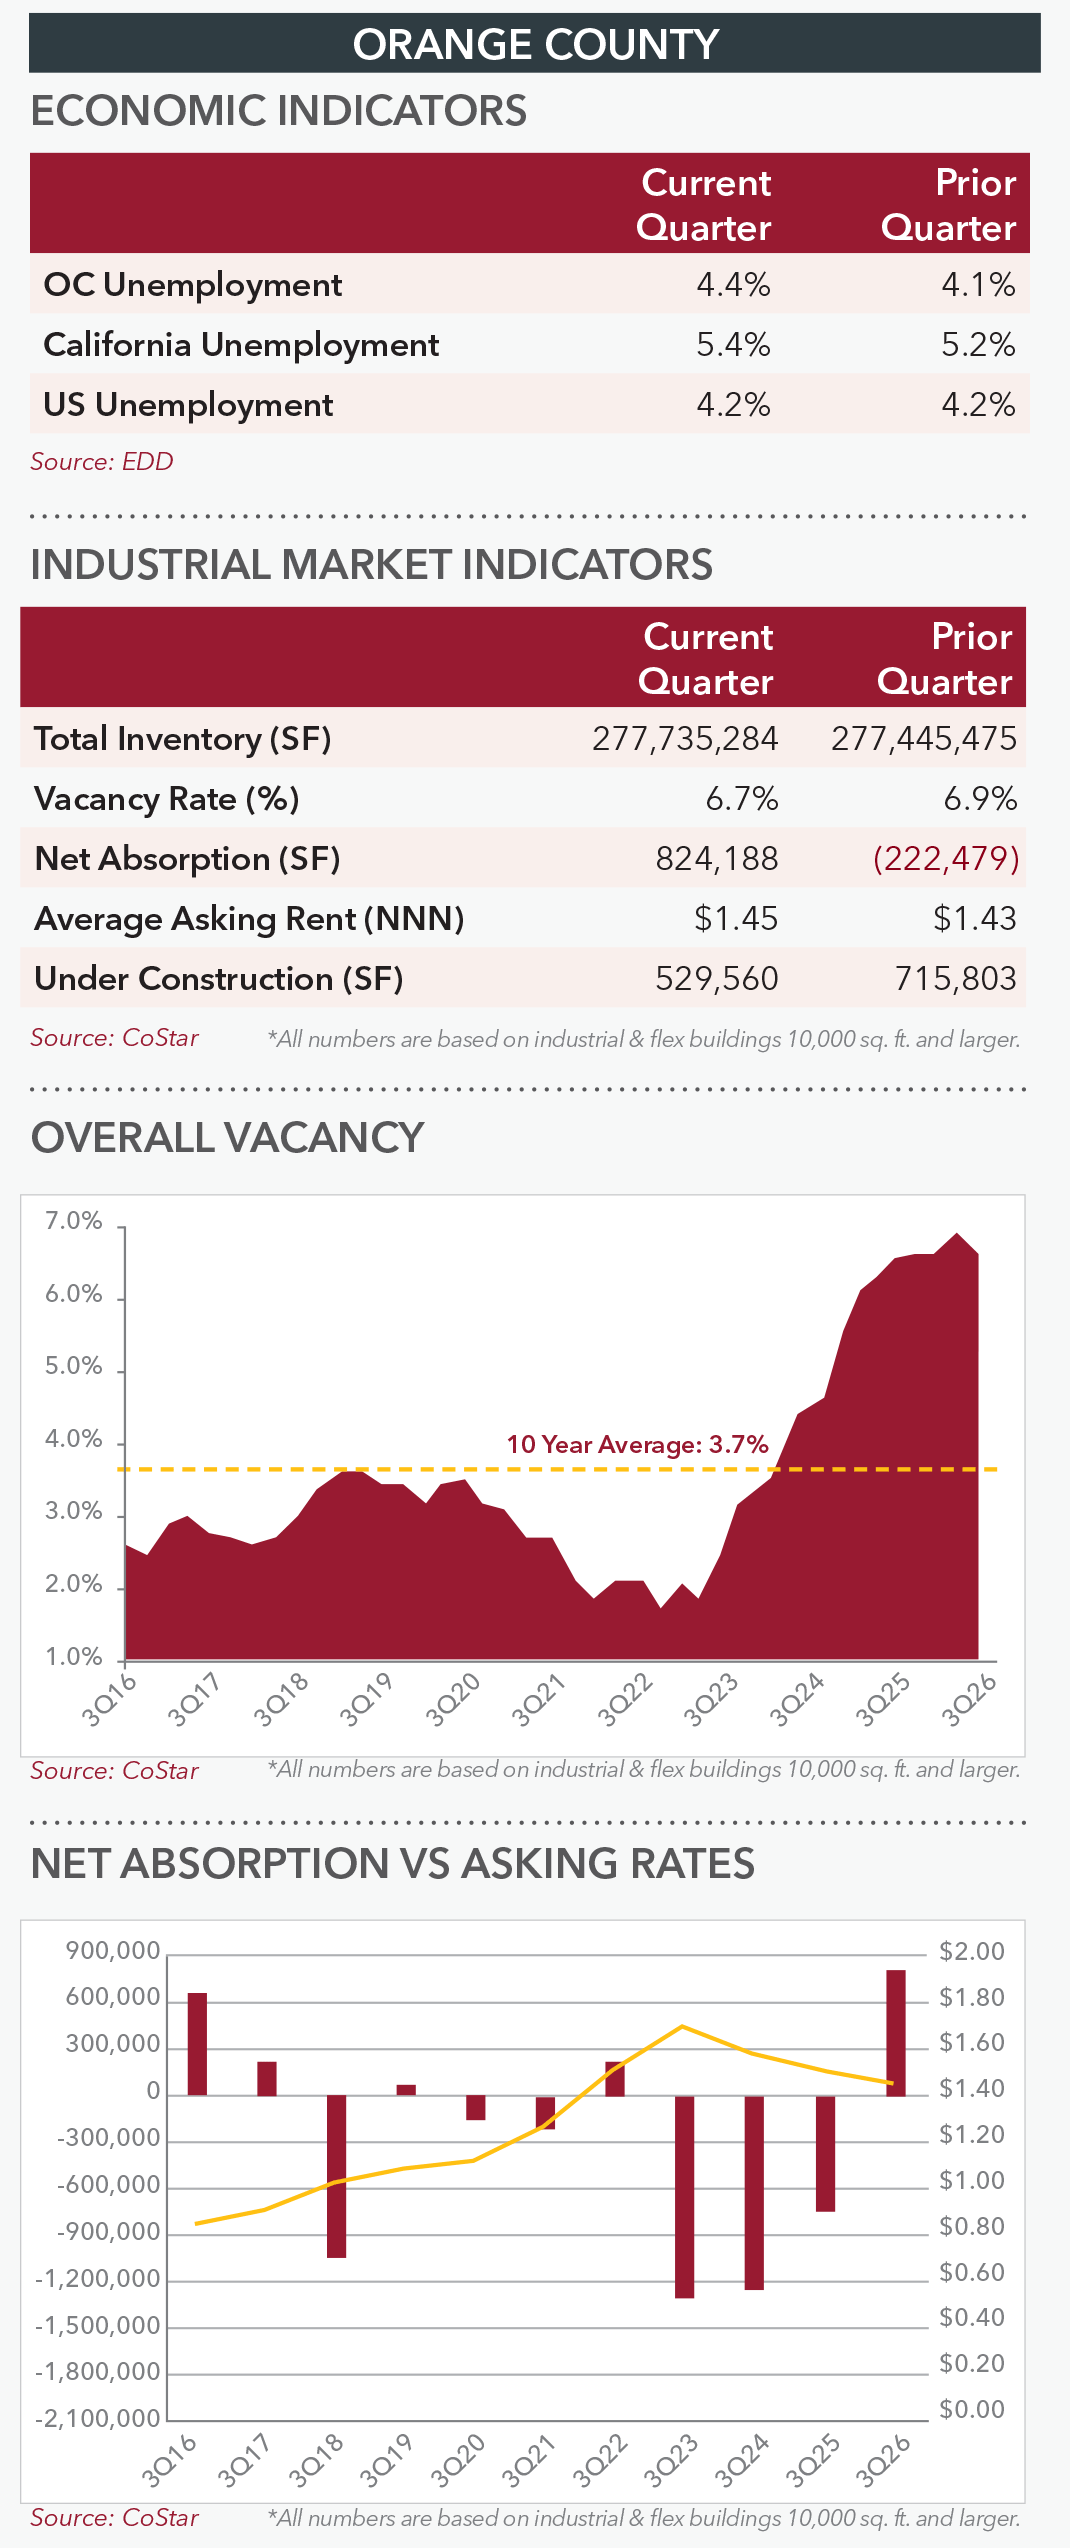
Net absorption totaled 824,188 SF in Q3. There has been positive overall tenant expansion of 1,440,309 SF in three of the last four quarters – a relief for landlords following 11 straight negative quarters during which occupancy declined more than 9.5 million SF.
There was healthy Q3 tenant expansion throughout most of the county. The overall vacancy rate ticked downward from 6.9% at midyear to settle at 6.7%. Three newly completed buildings totaling 304,230 SF boosted the county’s inventory to 277.7 million SF. The nearly 17% skid in asking rents was checked after a 10-quarter decline.
Among U.S. markets, Orange County’s inventory is ranked 22nd largest with vacancy at 46th lowest. It’s 30th in net absorption and ninth most in asking rents.
The 72.4-million-SF Airport market led the way with 530,896 SF of Q3 tenant growth. The Airport market also is the county’s tightest with a vacancy rate of 5.9%, down from 6.4% at midyear. The Airport market covers Costa Mesa, Fountain Valley, Irvine, Newport Beach, South Santa Ana and Tustin.
The North and West County markets also reported positive net absorption.
West County, with 44.3 million SF of inventory, reported a Q3 net gain of 379,552 SF throughout the cities of Cypress, Huntington Beach, Los Alamitos, Stanton, Seal Beach and Westminster.
North County, the county’s largest market with 117 million SF of space, recorded 133,259 SF of tenant growth. North County includes Anaheim, Brea, La Habra, Buena Park, Fullerton, La Palma, Placentia and Yorba Linda.
South County continues as the demand outlier with negative 248,000 SF of Q3 absorption. Covering 43.8 million SF from the Irvine Spectrum to San Clemente, South County tenants have put 1.8 million SF back in available inventory in the last four years, driving up the vacancy rate from 2.2% to 9%.
Asking full-service rents averaged $1.47 per SF in Q3, posting the first quarterly bump in three years since their $1.67 per SF historical peak. That high-water mark followed a post-recession, 12-year run-up from 64 cents per SF from Q3 2011.
The largest lease in the quarter was for an airport-close 136,612-SF, two-year-old logistics facility at 18582 Teller Ave. Developed on 6.25 acres by Marq Logistics for Ares Real Estate, the asking rent was $1.28 per SF. Other terms and the tenant’s name were undisclosed.
The largest sale in Q3 was the $75-million acquisition by Robinson Pharma from Starpoint Ventures of a 263,988-SF building with 26 feet of clear height at 2323 Main St., Irvine. The building initially was purchased in 2006 by Hines Interest LP for $31.5.
MARKET FORECAST
Cal State Fullerton’s Business Expectations Index for Orange County rose to 72.4% in Q3, up from Q2’s 68.5%. Inflation remains as the leading concern followed by fuel costs, interest rates, tariffs, government deficits, the Iran war and a potential stock market decline.