OFFICE RECOVERY CONTINUES, RENTS HIT NEW RECORD
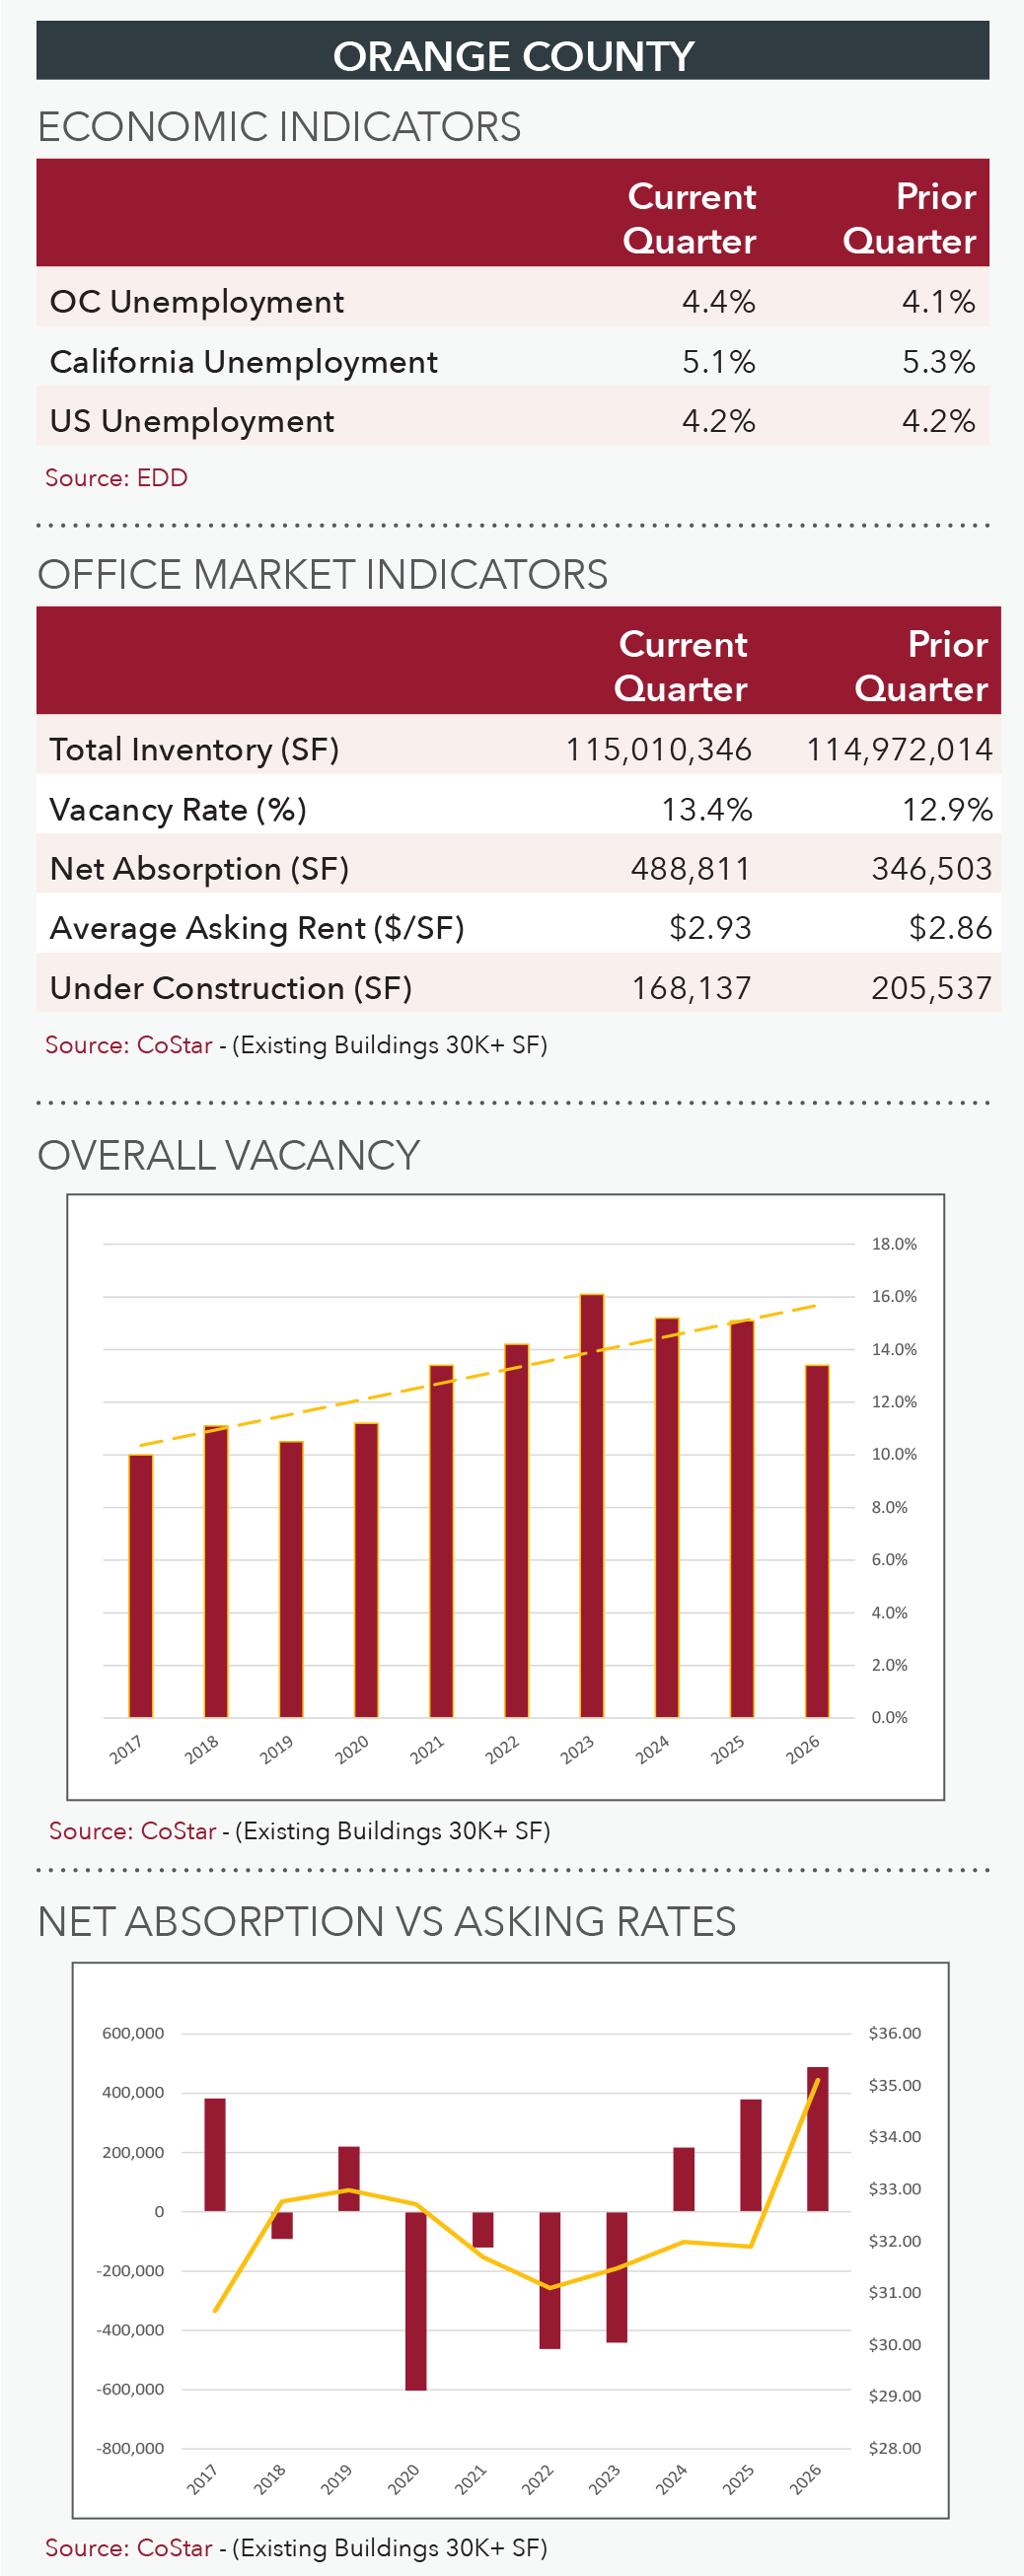
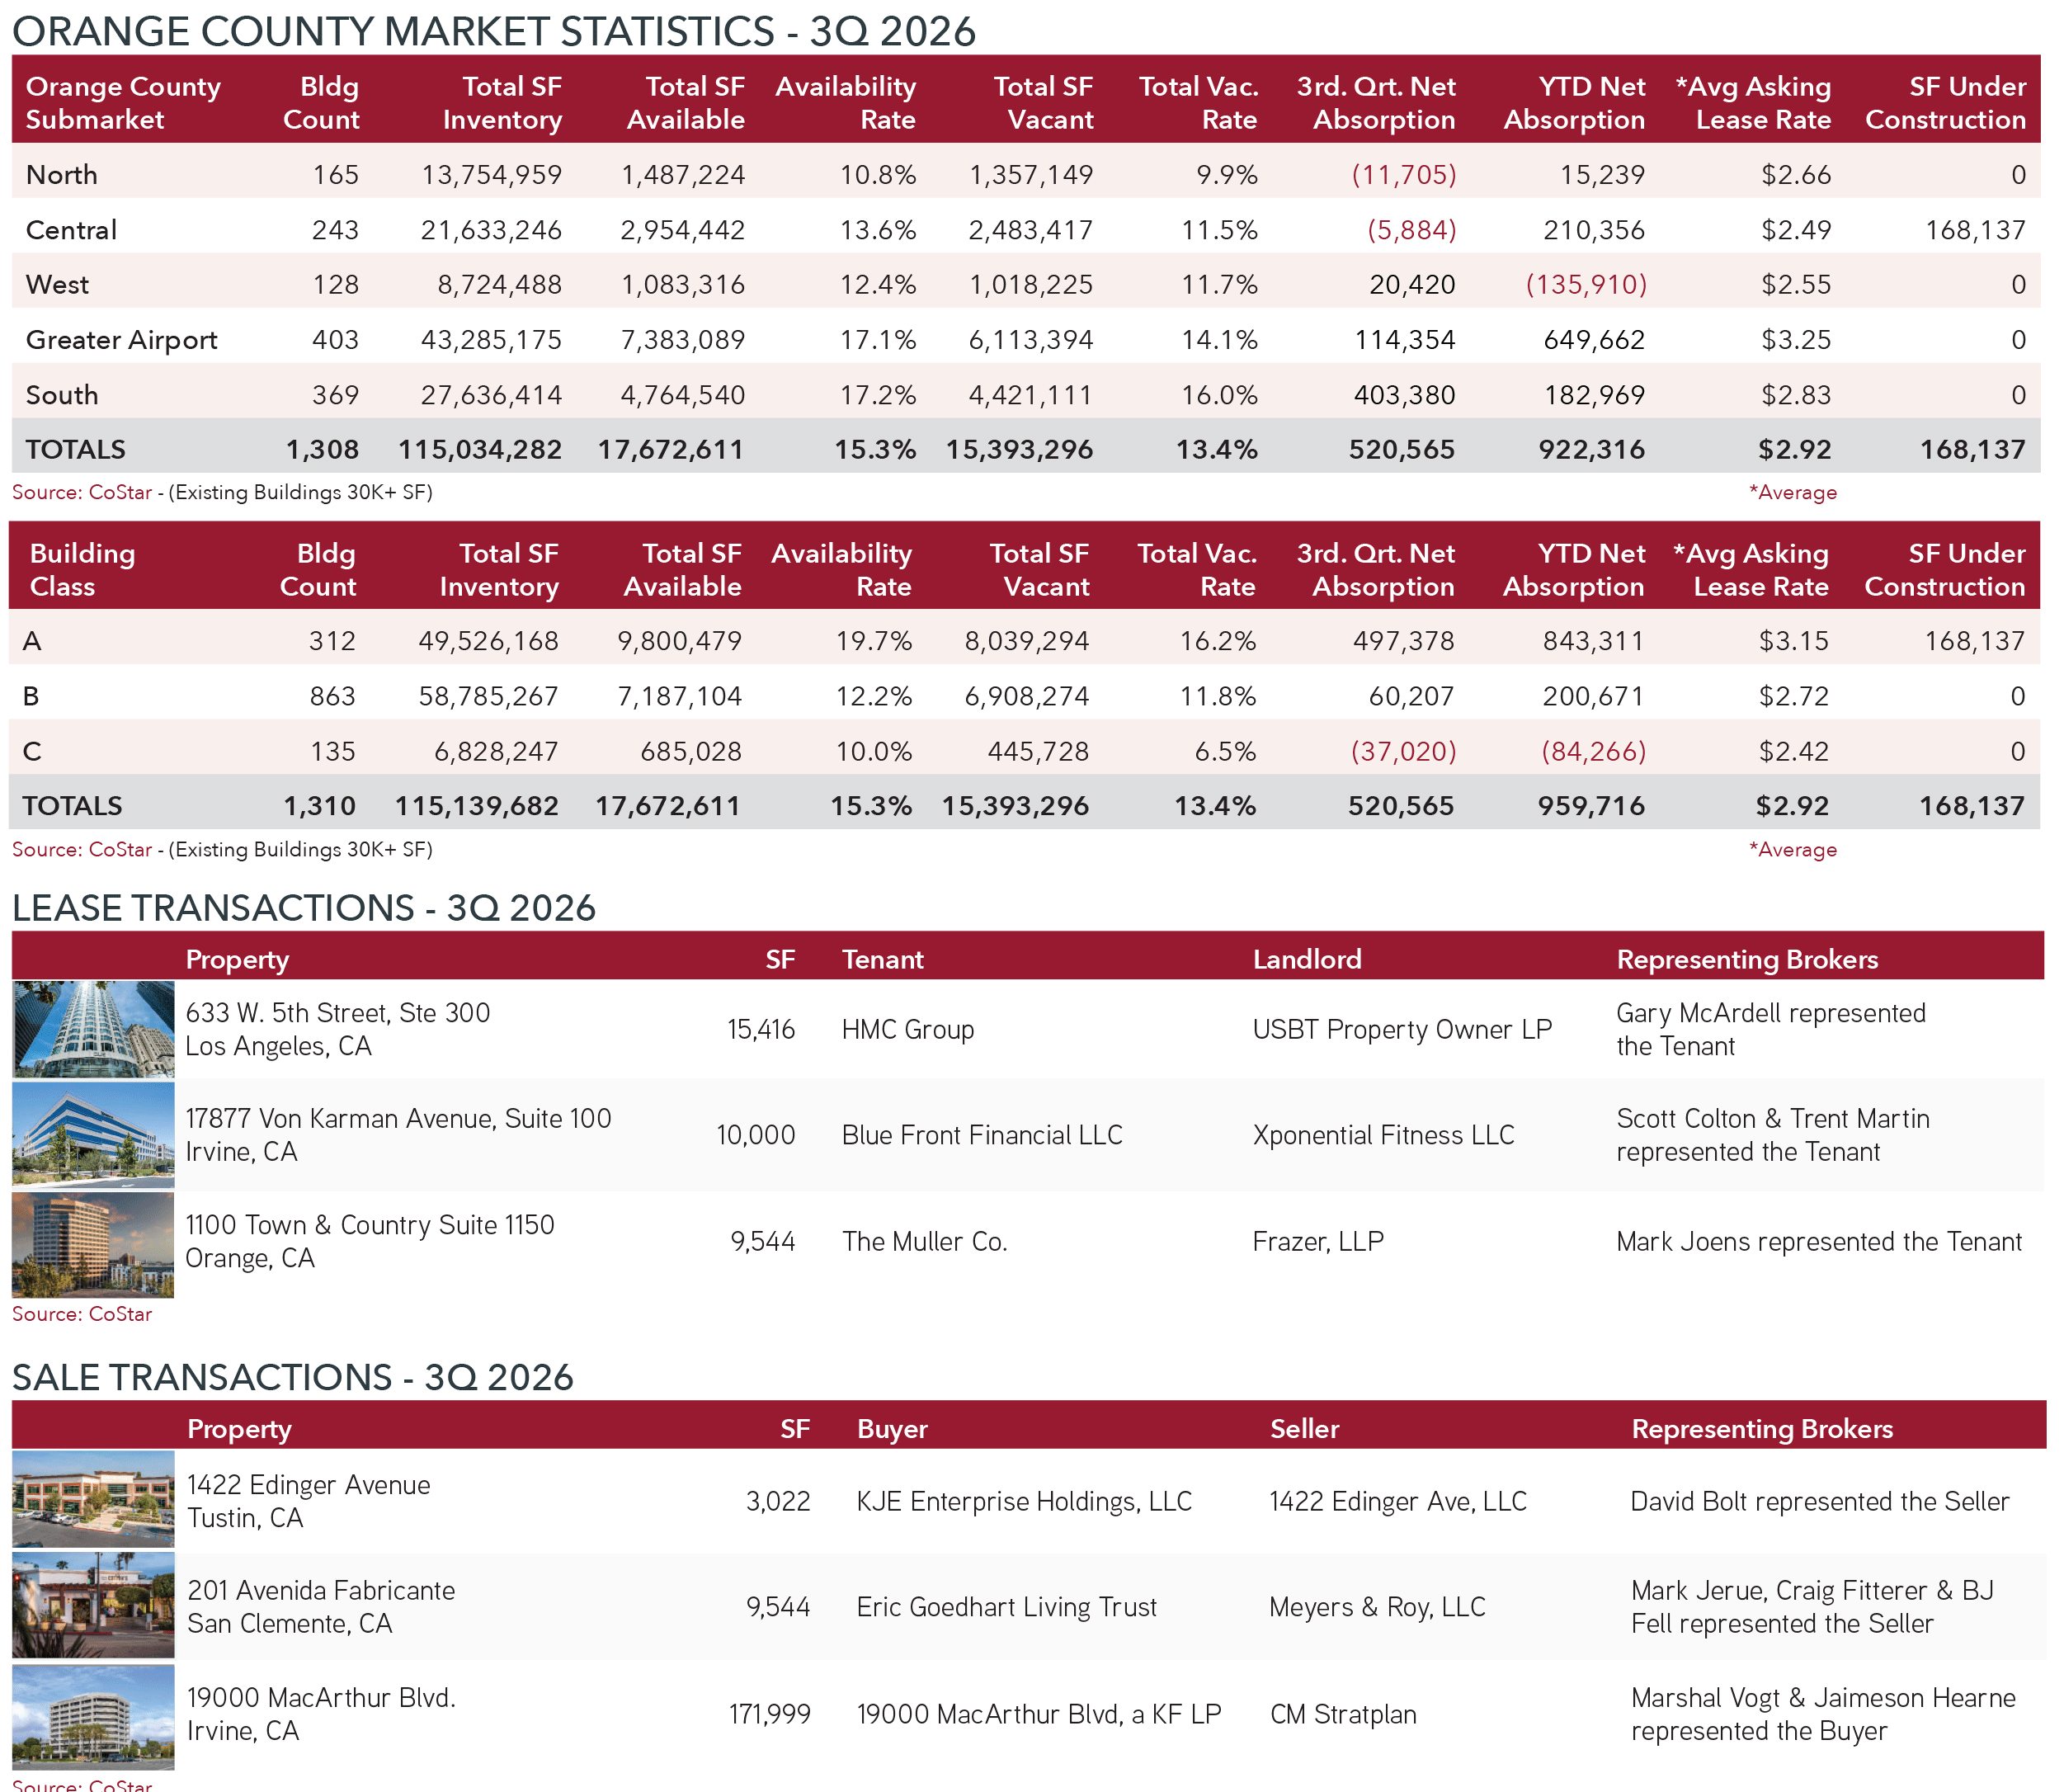
Healthy tenant growth continued in the third quarter with companies leasing nearly a half-million square feet of space. Steady gains in demand have pushed the vacancy rate down to 13.4% from its 16.1% peak reached three years ago and is slightly less than the nationwide average. Asking gross rents are up 10% year over year, averaging $2.93 per SF, the highest on record.
Positive net absorption in the last five quarters totals 2.6 million SF, with 3.7 million SF in 11 of the last 12 quarters. Available sublet space has fallen to 2,416,223 SF – less than its pre-pandemic average – from the record 4,234,301 SF in early 2023.
Class A space accounts for 43% of the county’s 115-millon-SF inventory and is capturing most of the growth. The vacancy rate for premium space settled at 16.3% in Q3, down from a record 21.5% three years ago. Available Class A sublet space totaled 1,231,332 SF at the end of Q3, the least since the end of 2019.
Countywide demand in Q3 was mixed as three of the county’s five submarkets reported absorption gains in Q3, led by South County with 371,626 SF. Tenant growth in Airport-area buildings totaled 114,354 SF in Q3 and is up 649,662 SF for the year. Four submarkets are showing year-to-date gains of 959,716 SF. Third-quarter North and Central county net absorption was slightly in the red.
Despite the improved growth, overall market activity also remains somewhat subdued with leasing volume and new deal flow more than 10% less than prior to Covid in 2020. Fewer tenants are relinquishing space, and owner occupancy has continued to increase with building acquisitions. Owner occupancy has expanded by more than 3.5 million SF since 2020, equivalent to more than 2% of countywide inventory, as owner-user acquisitions have exceeded user sales.
Office utilization is still gradually recovering from pandemic-era lows, but growth in local office-using employment remains limited. Consequently, weak employment trends represent a key risk to the forecast, which anticipates continued vacancy compression and firmer rent growth.
Only one speculative office building is under construction, located within the OCVIBE mixed use redevelopment in Anaheim. Supply levels will contract in the coming quarters as additional obsolete suburban office buildings are removed for redevelopment, most commonly residential projects.
The largest lease in Q3 was Taco Bell’s agreement with the Irvine Co. for a 104,294 SF, Class B building at 15955 Alton Parkway in the Irvine Spectrum. Asking rent was listed at $2.11 per SF.
The largest sale transaction was Hoag Memorial Hospital’s acquisition of the 1-million-SF Chet Holifield Federal Building, aka The Ziggurat, in Laguna Niguel from the U.S. General Services Administration for $207 million. Hoag officials said a “health and wellness village” is planned for the 89-acre campus.
MARKET FORECAST
Cal State Fullerton’s Business Expectations Index for Orange County rose to 72.4% in Q3, up from Q2’s 68.5%. Inflation remains as the leading concern followed by fuel costs, interest rates, tariffs, government deficits, the Iran war and a potential stock market decline.