
Q4 2025 Office Market Trends: How the Tri-Cities, Mid-Cities, and San Gabriel Valley Are Performing
Southern California Office Markets Show Diverging Trends Heading into 2026
(PASADENA, CA) – Southern California’s office sector continues to navigate a complex post-pandemic landscape. While demand and pricing vary across submarkets, recent data from the Tri-Cities, Mid-Cities, and San Gabriel Valley office markets suggests a period of stabilization with pockets of resilience. Across these markets, asking rents have generally remained strong even as vacancy levels and investment pricing adjust to evolving tenant needs and investor sentiment.
Below is a closer look at how each of these key submarkets performed during the fourth quarter of 2025.
Tri-Cities Office Market: Stabilization Amid Elevated Vacancy
The Tri-Cities office market—encompassing Glendale, Burbank, and Pasadena—showed modest signs of stabilization in the fourth quarter of 2025. Twelve-month net absorption turned positive at 7,345 square feet, signaling a potential rebound following periods of volatility earlier in the year.
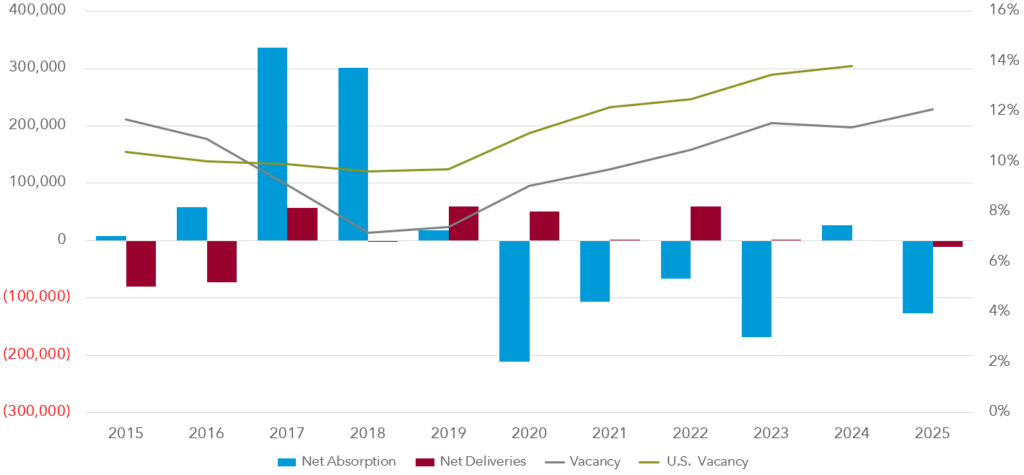
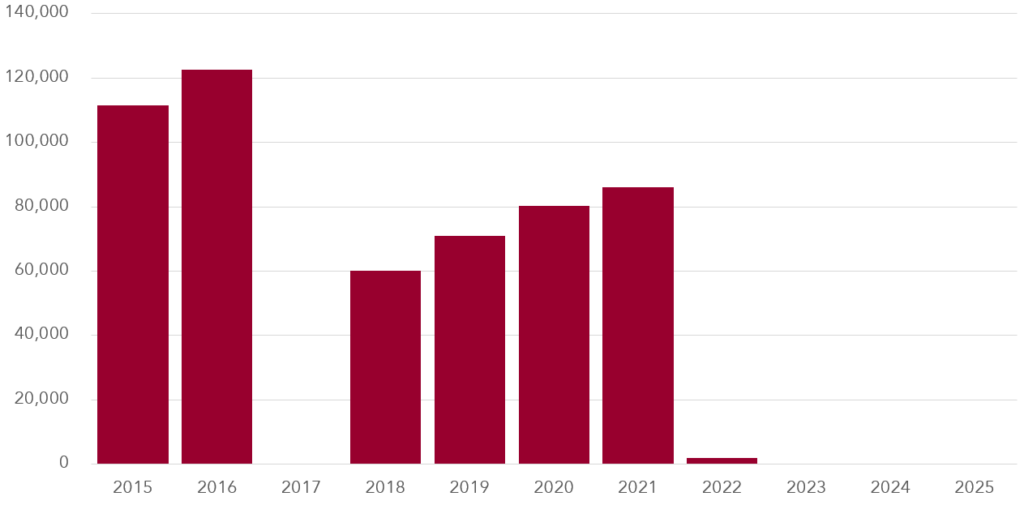
Despite improving absorption, vacancy rose to 26.1%, reflecting the continued availability of office space across the market. However, landlords demonstrated pricing resilience as average NNN asking rents increased to $47.04 per square foot annually.
Investment activity also reflected broader market adjustments. Office sales averaged $322 per square foot, while cap rates expanded to 7.8%, suggesting investors continue to recalibrate pricing expectations in response to higher interest rates and shifting demand.
Several notable leasing transactions occurred during the quarter, including:
-
55,000 SF at 115 N. 1st Street in Burbank leased by Concord Career Colleges
-
48,882 SF at 177 E. Colorado Boulevard leased by Arrowhead Pharmaceuticals
-
48,002 SF at 801 N. Brand Boulevard
On the investment side, the most significant transaction was Amazon’s $78.8 million acquisition at 2964 Bradley Street, underscoring continued institutional interest in select office assets.
Mid-Cities Office Market: Tight Vacancy and Rising Rents
In contrast to the Tri-Cities, the Mid-Cities office market remains one of the tightest office markets in the region.
Although 12-month net absorption declined by 22,963 square feet, vacancy actually improved to just 3.6%, highlighting the limited availability of office inventory within this submarket.
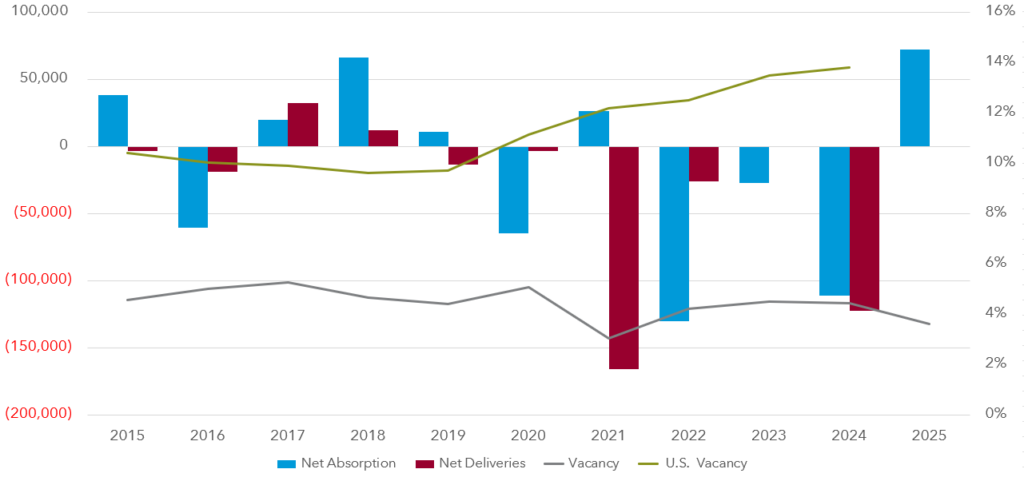
Pricing strength was particularly evident in rental rates. Average NNN asking rents rose sharply to $33.09 per square foot annually, demonstrating continued demand for available space despite broader industry headwinds.
Investment metrics showed some adjustment. Average sales pricing declined to $250 per square foot, while cap rates expanded to 7.96%, reflecting a more cautious investment environment as buyers account for higher borrowing costs.
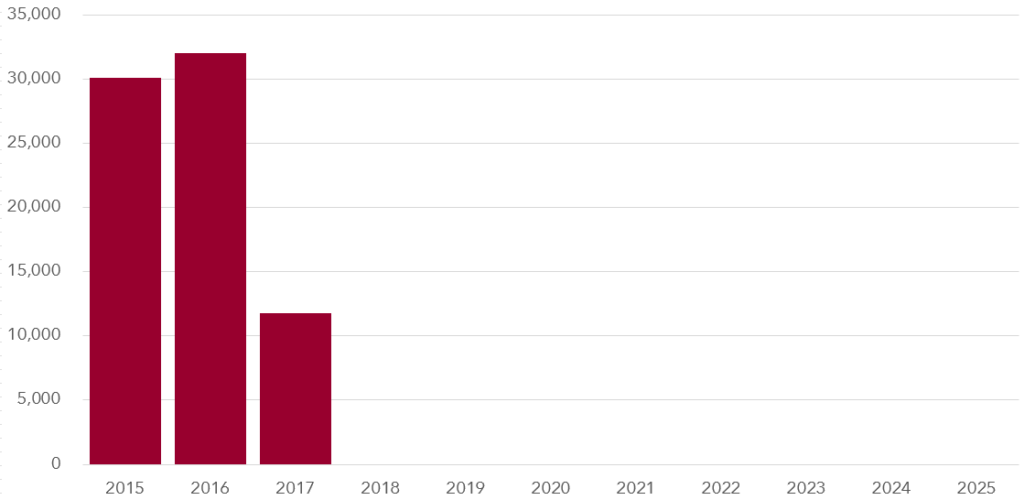
Notably, no new office construction was underway during the quarter, which could further constrain supply in the near term.
Key leasing transactions included:
-
4,922 SF at 2675–2677 Zoe Avenue
-
4,621 SF at 10350 Heritage Park Drive
-
4,000 SF at 5608 Soto Street
The largest investment sale was AltaMed’s $9.5 million acquisition at 2675 E. Slauson Avenue.
San Gabriel Valley Office Market: Softening Demand with Limited Supply Growth
The San Gabriel Valley office market experienced modest softening during the fourth quarter, as 12-month net absorption declined by 88,014 square feet, reversing gains from earlier in the year.
Vacancy edged slightly higher to 6.32%, though it remains relatively tight compared to many other regional office markets.
At the same time, average NNN asking rents increased to $32.28 per square foot annually, reflecting continued landlord confidence and the limited availability of high-quality office space.
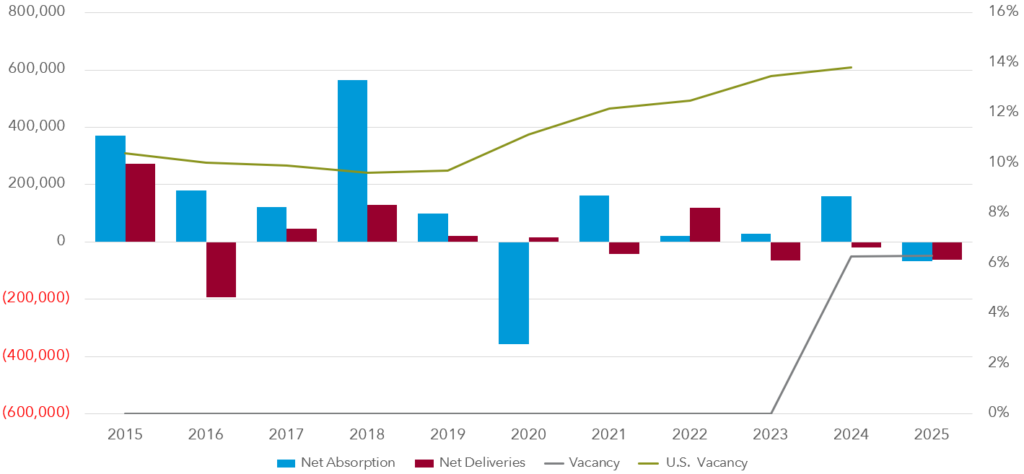
Sales pricing held relatively stable at $278 per square foot, while cap rates expanded to 7.73%, signaling ongoing investor caution amid broader market uncertainty.
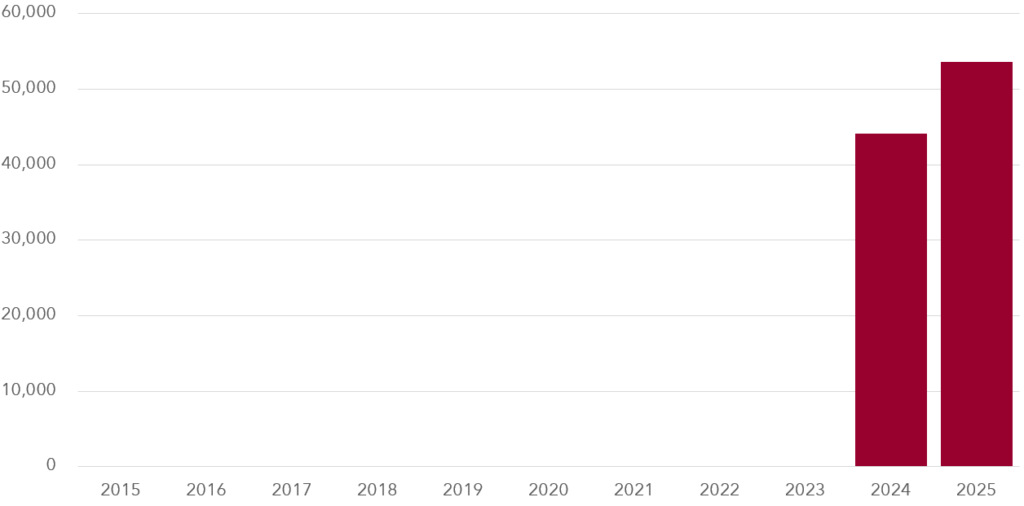
Unlike the Mid-Cities market, the San Gabriel Valley does have approximately 53,626 square feet of office space currently under construction, which will introduce a modest amount of new inventory in the near future.
The largest leasing transactions included:
-
49,252 SF at 924 Overland Court
-
19,574 SF at 21 Rancho Camino Drive
-
18,391 SF at 181 W. Huntington Drive
The most notable investment sale was Western University’s $13.3 million acquisition at 300 S. Park Avenue.
Key Takeaways Across the Region
Across these three Southern California office markets, several trends stand out:
1. Asking rents remain resilient.
Despite fluctuations in demand and rising vacancies in certain areas, landlords have largely maintained or increased rental rates.
2. Investment markets are adjusting.
Cap rates have expanded across all three submarkets, reflecting a more cautious investment environment and higher financing costs.
3. Supply growth remains limited.
Very little new office development is underway, particularly in the Mid-Cities, which could support long-term occupancy levels.
4. Market performance varies significantly by submarket.
While the Tri-Cities market faces elevated vacancy, the Mid-Cities and San Gabriel Valley continue to maintain relatively tight conditions compared to broader office markets.
Outlook for 2026
As the office sector continues to evolve, the coming year will likely be defined by continued price discovery, tenant rightsizing, and selective investment activity. Submarkets with limited supply and strong tenant demand may continue to demonstrate resilience, while others work through elevated vacancy and shifting workplace dynamics.
Overall, the data suggests that while the office market remains in transition, stability is beginning to emerge in several key Southern California submarkets.
Christopher Larimore is a Founding Principal and former President of Lee & Associates – Pasadena, Inc., Mr. Larimore continuously strives to optimize the full service brokerage experience for clients to include opening the Property Management service line. He serves as President and Managing Principal for Lee & Associates Pasadena Property Management. As an active agent, Mr. Larimore specializes in sales & leasing of office, medical and neighborhood retail properties in the San Gabriel Valley, Tri-Cities and Mid-Cities South Los Angeles markets.
| Connect with Us: (Scan or Click QR Code)  |
###
ABOUT LEE & ASSOCIATES – PASADENA, INC.
Lee & Associates – Pasadena is a full service commercial real estate company headquartered in Pasadena, CA. Our client-focused brokers specialize in office, retail, tenant advisory, multifamily, and investment sales. As the fastest-growing broker-owned firm in the nation, with more than 60 office locations in North America, we are uniquely qualified to support our clients’ real estate needs in the local, national and international markets. For more information, visit lee-pasadena.com.
###