April 2026 | Market Brief
The office market is often framed as waiting on demand to return, but in Atlanta, that narrative is incomplete. Leasing activity has remained relatively consistent, while the more meaningful shift in market conditions is being driven by something less visible: inventory.
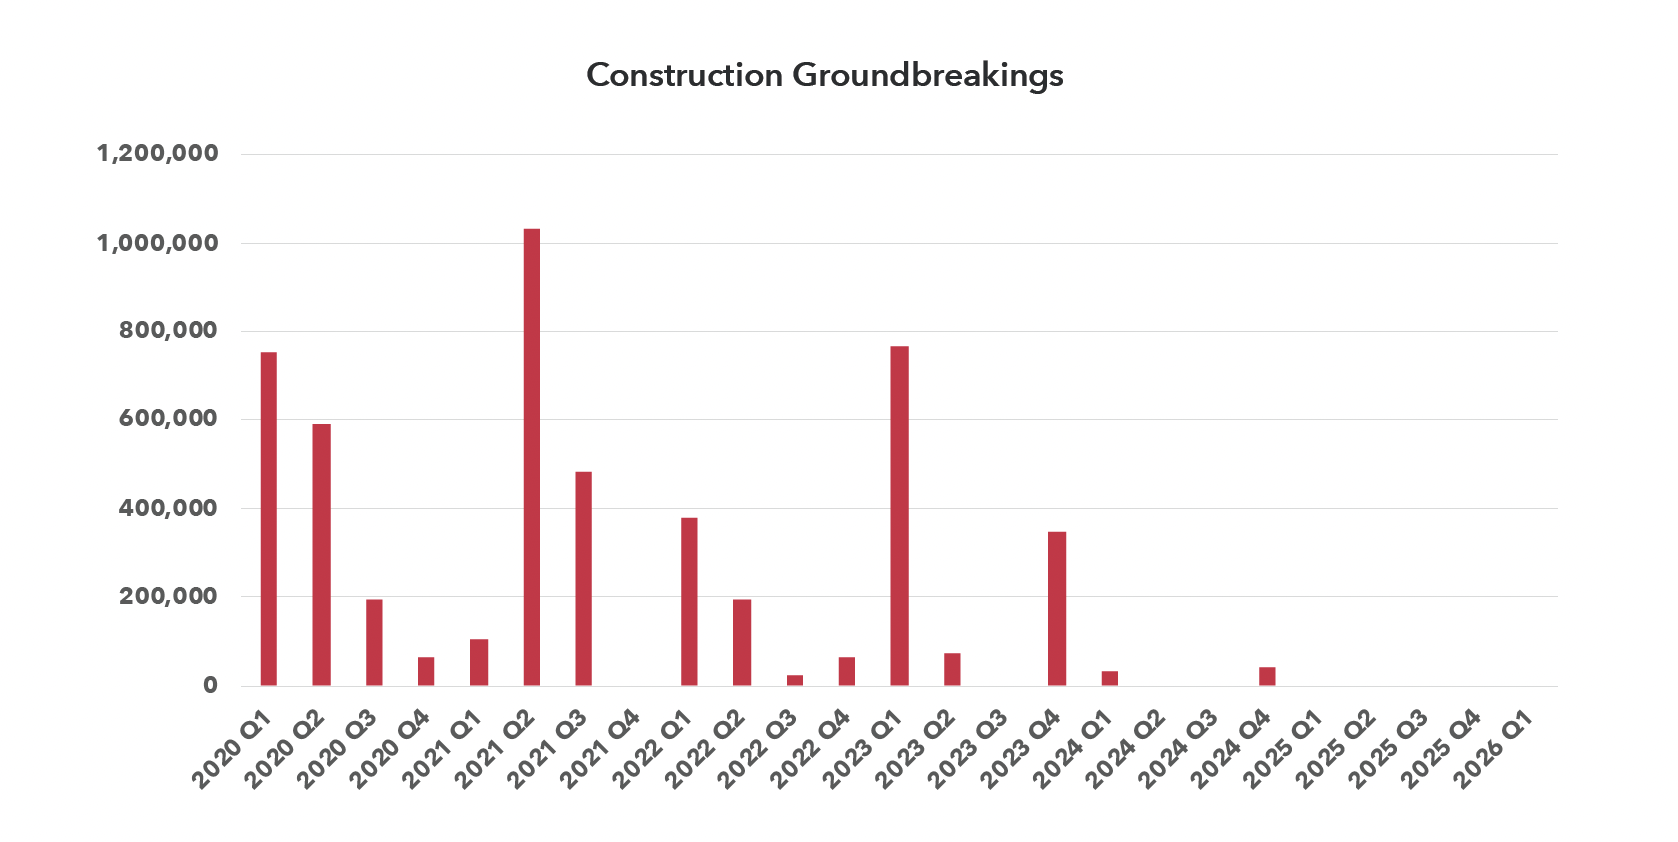
Vacancy remains elevated, hovering near 25%, but the underlying pressure has changed. For most of the past cycle, even modest demand gains were offset by a steady pipeline of new deliveries. That dynamic has now reversed. Ground-up construction has largely stalled, and net inventory is beginning to contract after years of expansion. For the first time in years, demand is no longer competing with meaningful new supply.
At the same time, Atlanta has emerged as one of the most active markets nationally for office-to-multifamily conversions, leading to more space being removed than added. However, the impact of this trend is inherently limited, as not all office properties are viable candidates for conversion. Only about 6% of Atlanta’s inventory meets the physical and economic criteria for adaptive reuse, according to ConnectCRE. While conversion activity is accelerating, most obsolete space will remain, extending the market’s adjustment timeline. The combination of limited new construction, targeted inventory reduction, and steady demand is beginning to stabilize availability. The decline in available space is not being driven solely by tenant expansion, but by a market where supply is no longer working against itself.
Atlanta’s office recovery will not be defined by a surge in demand, but by the gradual reduction and realignment of excess inventory to better match a smaller, more efficient occupier base.