
Houston Industrial Distribution | Market Report Q1 2026
Executive Summary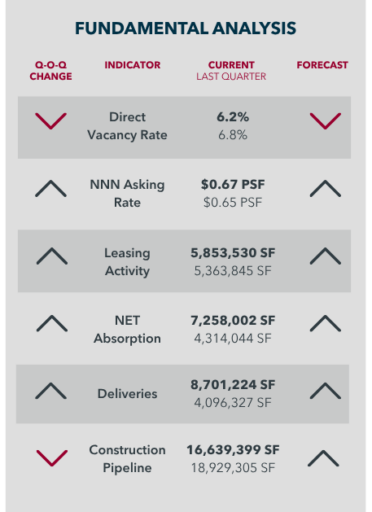
Port and manufacturing driven demand and disciplined development continue to anchor Houston’s industrial market, with Southeast Houston remaining a key driver of long-term growth.
Houston’s industrial distribution market entered Q1 2026 on stable footing, with balanced fundamentals supported by steady tenant demand, moderated construction activity, and pricing that has stabilized at an elevated baseline. The citywide weighted NNN asking rate increased to $0.67 per square foot, while vacancy declined to 6.2%, reflecting continued absorption of recent deliveries and sustained leasing activity across core submarkets.
The Southeast submarket remains a focal point of market strength, driven by its direct connectivity to Port Houston and its role as a primary hub for import/export, manufacturing, and logistics users. Continued growth in container volumes, supply chain diversification, and renewed strength in the manufacturing sector has reinforced demand for well-located space in this corridor, particularly for cross-dock, port-oriented, and facilities with heavier power.
Leasing activity remains healthy, with tenants prioritizing efficiency, access to infrastructure, and modern building specifications. While new deliveries have introduced short-term vacancy pressure in select submarkets, absorption trends indicate that supply is being effectively digested.
Looking ahead, Houston is well-positioned for continued stability, with low single-digit rent growth expected as development remains disciplined and port-driven demand continues to support long-term industrial fundamentals.
– JUSTIN TUNNELL, SIOR | PRINCIPAL
KEY TAKEAWAYS
- Rates have stabilized at a higher baseline, with continued pricing support despite new deliveries.
Rates reached $0.67 per square foot, reflecting a transition from rapid growth to sustained, demand-supported pricing.
- Recent vacancy pressure remains timing-driven rather than demand-driven.
Vacancy declined to 6.2%, reinforcing that recent increases were largely timing-driven rather than demand-related.
- Leasing demand remains concentrated in core logistics corridors, particularly Southeast and Northwest submarkets.
Tenant activity continues to favor locations with direct access to port infrastructure and major transportation networks.
- Development remains active but increasingly selective.
Developers are aligning starts more closely with leasing velocity, reflecting a shift from expansion to disciplined execution.
- Cross-dock and bulk distribution assets continue to drive leasing velocity and absorption.
Larger users remain focused on throughput, trailer capacity, and operational efficiency.
- Capital markets remain liquid but selective, with strongest demand for stabilized Class A assets.
Pricing remains firm, with modest cap rate movement and continued competition for core product.
Asking Rate vs Vacancy Rate
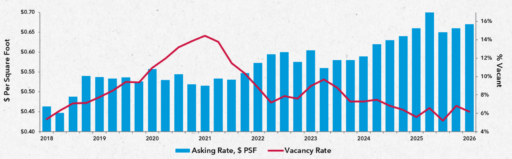
The Houston industrial distribution market entered Q1 2026 showing continued stabilization following the normalization phase observed throughout 2025. Average asking rates increased 3.1% quarter-over-quarter to $0.67 per square foot, up from $0.65 per square foot in Q4 2025, reflecting steady leasing activity and sustained landlord discipline despite some short-term pricing volatility.
Vacancy declined 60 basis points to 6.2% from 6.8% last quarter, a 9.7% tightening. This compression aligns with the broader trend of stabilization, as vacancy has remained within a relatively tight range since early 2024. Recent movement is largely attributable to the absorption of new deliveries rather than any meaningful shift in tenant demand.
At the submarket level, performance continues to vary. The Southeast and Port of Houston corridors remain among the tightest in the market, supported by strong import/export activity and proximity to major logistics infrastructure. The Northwest and North submarkets continue to see elevated leasing velocity but face more near-term vacancy pressure due to higher concentrations of recent speculative development. Meanwhile, closer-in “infill” locations along the I-10 and I-45 corridors continue to command premium rents, driven by limited availability and last-mile demand.
Overall, with balanced fundamentals, disciplined development, and steady tenant demand, Houston’s industrial market is positioned to maintain stability through 2026
Net Absorption vs Deliveries
What We’re Watching
- Lease-Up velocity of recent bulk deliveries
- Vacancy pressure in Northwest and North submarkets
- Delivery pipeline relative to absorption through Mid-2026
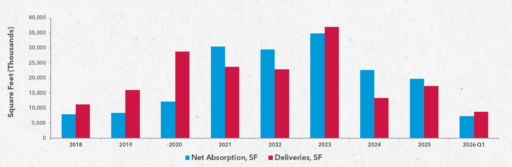
The Houston industrial distribution market maintained positive momentum in Q1 2026, supported by continued tenant activity and steady absorption of new supply. Net absorption totaled 7.3 million square feet during the quarter, marking a moderation from the elevated levels recorded in late 2025 but remaining consistent with normalized demand trends.
Deliveries reached 8.7 million square feet in Q1 2026, reflecting a wave of projects delivering early in the year. While completions outpaced absorption during the quarter, the gap remains manageable and largely attributable to timing, as newly delivered space continues to lease up. This dynamic has contributed to modest upward pressure on vacancy but does not indicate a fundamental shift in demand.
On a year-over-year basis, absorption remains resilient, supported by occupiers in logistics, manufacturing, and construction sectors. Demand continues to concentrate in core distribution corridors, particularly near the Port of Houston and along major transportation routes. Near-term vacancy fluctuations are expected as deliveries continue, but current absorption trends indicate no structural oversupply.
Over the longer term, Houston’s industrial market has demonstrated its ability to absorb significant new supply. Since 2018, the market has added 188.7 million square feet of distribution inventory, with strong cumulative absorption helping to maintain equilibrium. With a moderating construction pipeline and steady tenant demand, the market remains well-positioned for continued stability through 2026.
Leasing Activity
Tenant Trends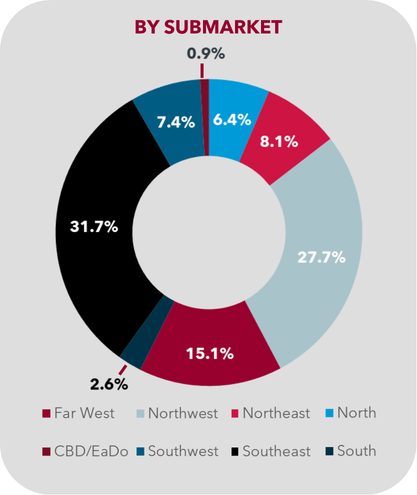
- Shift toward footprint optimization rather than expansion
- Increased demand for trailer parking and yard space
- Continued preference for modern bulk distribution product
Houston’s industrial distribution market closed Q1 2026 with steady, measured leasing activity and sustained tenant demand concentrated across core logistics corridors. Total leasing volume reached 5.9 million square feet during the quarter, bringing year-to-date activity to the same level.
- Although quarterly volume increased relative to Q4 2025’s 5.4 million square feet, Q1 2026 results aligned with typical seasonal patterns and compared favorably to historical benchmarks. Leasing totaled 6.5 million square feet in Q1 2025 and 7.5 million square feet in Q1 2024, reflecting the influence of timing and deal execution rather than any material shift in underlying demand.
- Leasing activity remained concentrated in the Southeast, Northwest, and Far West submarkets, which together accounted for over 74.5% of quarterly absorption. These submarkets continue to attract tenants due to proximity to major highway networks, Port Houston, rail infrastructure, and rapidly growing industrial nodes. Tenant requirements were driven by a combination of expansion and consolidation strategies, with operational efficiency, trailer parking, and modern clear heights serving as key decision factors.
- While availability of large contiguous blocks has expanded following a robust quarter of deliveries, tenants seeking 250,000 square feet or more increasingly consider pre-leasing, phased occupancy, or build-to-suit solutions. This dynamic is sustaining leasing velocity while supporting pricing for strategically located Class A product.
- Overall, Houston’s industrial leasing environment remains resilient entering 2026, underpinned by a diversified tenant base, disciplined supply growth, and continued demand from distribution, manufacturing, and infrastructure sectors.
Construction Pipeline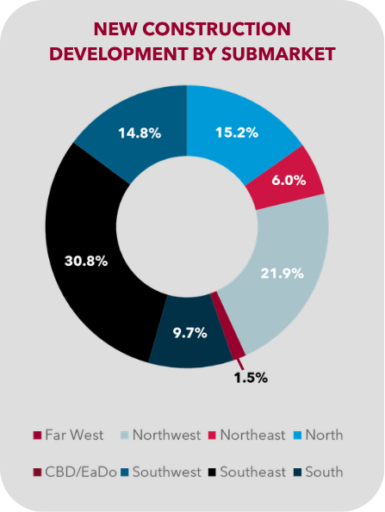
Houston’s industrial distribution development pipeline remained active in Q1 2026, reflecting elevated construction levels following several years of strong expansion. Total space under construction reached 16.6 million square feet, with most projects remaining speculative, signaling developer confidence in long-term fundamentals alongside a more disciplined approach to new starts.
- Construction activity remained concentrated in the Southeast, Northwest, North, and Southwest submarkets, which together accounted for 82.7% of development. These areas continue to attract projects due to access to major transportation infrastructure, proximity to labor, and their roles as established logistics hubs.
- New construction starts totaled 6.4 million square feet during the quarter, increasing from Q4 2025 but remaining measured relative to prior cycles. Developers continue aligning new starts with leasing velocity, absorption trends, and capital market conditions, reflecting a more selective approach to project timing.
- A total of 56 buildings were under construction during the quarter, with an aggregate pre-leasing rate of 20.6%, unchanged from Q4 2025, as new speculative supply offset leasing gains. Pre-leasing remains modest but consistent with current conditions, as tenants favor flexibility amid evolving space requirements. This reflects a broader shift toward optimization, as occupiers focus on efficiency, network positioning, and cost control.
- Looking ahead, rising construction and financing costs are expected to moderate near-term development activity, while steady tenant demand and continued absorption in core submarkets support targeted development through 2026.
Load Configuration Analysis
| SUBMARKET | CROSS-DOCK ASKING RATE |
CROSS-DOCK AVG. DEAL SF |
FRONT-LOAD ASKING RATE |
FRONT-LOAD AVG. DEAL SF |
REAR-LOAD ASKING RATE |
REAR-LOAD AVG. DEAL SF |
MARKET AVG. ASKING RATE |
MARKET AVG. DEAL SF |
|---|---|---|---|---|---|---|---|---|
| North | $0.63 | 54,200 | $0.72 | 148,707 | $0.80 | 12,254 | $0.71 | 66,854 |
| Northeast | n/a | n/a | $0.62 | 96,135 | $0.62 | 17,023 | $0.62 | 79,453 |
| Northwest | $0.65 | 101,825 | $0.72 | 53,735 | $0.78 | 71,184 | $0.69 | 49,187 |
| Far West | $0.65 | 305,621 | $0.70 | 88,113 | $0.74 | 97,285 | $0.69 | 176,950 |
| South | $0.65 | 90,000 | $0.73 | 29,857 | $0.83 | n/a | $0.70 | 49,904 |
| Southeast | $0.64 | 396,562 | $0.70 | 106,681 | $0.61 | 26,100 | $0.64 | 185,587 |
| Southwest | $0.64 | 52,467 | $0.69 | 73,204 | $0.85 | 39,344 | $0.70 | 48,326 |
| CBD/EaDo | $0.55 | 53,522 | n/a | n/a | n/a | n/a | $0.55 | 53,522 |
| DISTRIBUTION TOTALS |
$0.63 | 193,183 | $0.71 | 107,684 | $0.72 | 32,099 | $0.67 | 97,715 |
Rental rates remained balanced in Q1 2026, with pricing and leasing activity continuing to vary by building configuration.
Houston’s industrial distribution market maintained solid rental performance across all loading configurations in Q1 2026, reflecting a balanced leasing environment and continued alignment between tenant requirements and building functionality. The citywide weighted NNN asking rate increased 3.1% to $0.67 per square foot, up from $0.65 per square foot in Q4 2025, representing a modest quarter-over-quarter gain and continued pricing support despite ongoing deliveries. Annual escalations remain consistent, averaging between 3.50% and 3.75%.
Rear-load product continues to command the highest rents, with weighted asking rates at $0.72 per square foot. Demand remains
driven by smaller, infill-oriented users seeking functional space near population centers, with average deal sizes around 32,000 square feet.
Front-load assets posted weighted asking rates of $0.71 per square foot, attracting mid-sized tenants with average deal sizes near 74,000 square feet, serving as a balance between scale and functionality.
Cross-dock facilities remain the most competitively priced at $0.63 per square foot while capturing the largest average deal sizes, exceeding 170,000 square feet. Demand for these assets continues to be driven by logistics users prioritizing throughput and circulation efficiency.
Overall, the market remains highly segmented, with rent levels and leasing velocity increasingly dictated by building configuration, tenant size, and location.
Submarket Rate Comparison
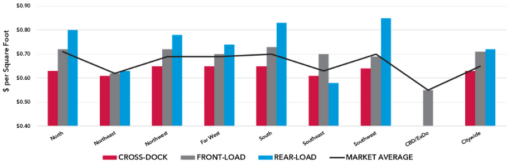
Asking rates remained stable in Q1 2026, with pricing dispersion across submarkets continuing to reflect location, product type, and tenant demand.
Houston’s industrial distribution market recorded a citywide weighted NNN asking rate of $0.67 per square foot in Q1 2026, reflecting modest growth from $0.65 in Q4 2025 and continued pricing support as new supply is absorbed. Rent levels remain near cyclical highs, with performance increasingly driven by submarket positioning and building configuration.
At the submarket level, higher average asking rates were observed in the North ($0.71), South ($0.70), and Southwest ($0.70), supported by a combination of newer product, strong logistics connectivity, and sustained tenant demand. The Northwest and Far West submarkets remained competitive at approximately $0.69, continuing to capture significant leasing activity given their concentration of bulk distribution space.
Lower average rents were recorded in the Northeast ($0.62) and Southeast ($0.64), reflecting a higher share of older inventory and more price-sensitive tenant demand. CBD/EaDo remained limited in industrial inventory, with smaller-format product commanding approximately $0.55 per square foot.
By configuration, rear-load product continued to command the highest pricing across most submarkets, particularly in the South and Southwest, where rates reached up to $0.83 and $0.85 per square foot, respectively. Cross-dock pricing remained more competitive, while front-load assets continued to serve as a middle tier between scale and functionality.
As a result, rent growth is no longer uniform across the market, with outperformance increasingly concentrated in submarkets offering modern product and superior access to regional infrastructure. Performance continues to diverge by product type, with bulk distribution and cross-dock assets outperforming smaller, older inventory.
Key Activities
| COMMENCEMENTS | |||
| TENANT | BUSINESS PARK | SQUARE FEET | SUBMARKET |
| Grainger | Grainger Distribution Center | 1,281,280 | Northwest |
| Undisclosed | Twinwood Distribution Center | 767,520 | Far West |
| Undisclosed | Port 99 Distribution Center | 623,131 | Southeast |
| LEASING ACTIVITY | |||
| TENANT | BUSINESS PARK | SQUARE FEET | SUBMARKET |
| Undisclosed | Port 99 Distribution Center | 623,131 | Southeast |
| Sanmina Corp. | Constellation Eldridge | 537,375 | Northwest |
| eLogistics | Kingsland Ranch Logistics Park | 430,000 | Far West |
| SALE TRANSACTIONS | |||
| BUYER | SELLER | BUSINESS PARK | SQUARE FEET | SUBMARKET |
| BGO | Stream Realty Partners, LP | Empire West Business Park (2 buildings) | 1,655,523 | Far West |
| TAS Energy, Inc. | Trammell Crow | Blue Ridge Commerce Center (2 buildings) | 782,015 | Southwest |
| Investcorp | Longpoint Realty Partners, LP | Willowbend Business Park (5 buildings) | 519,628 | Southwest |
| DELIVERIES | |||
| DEVELOPER / OWNER | BUSINESS PARK | SQUARE FEET | SUBMARKET |
| Hines | Grainger Distribution Center | 1,281,280 | Northwest |
| Hillwood Development | Pinnacle Logistics Park | 895,000 | Northwest |
| Falcon Commercial Development | Kingsland Ranch Logistics Park | 504,370 | Far West |
| CONSTRUCTION PIPELINE | |||
| DEVELOPER / OWNER | BUSINESS PARK | SQUARE FEET | SUBMARKET |
| Transwestern Development Company | Innerbelt Northwest | 1,229,480 | Northwest |
| Alliance Industrial Partners | TriPort 8 Logistics Park | 881,521 | Southeast |
| TGS Cedar Port Partners | TGS Cedar Port Industrial Park | 841,020 | Southeast |
Overall Submarket Statistics
| SUBMARKET | INVENTORY (SF) |
DIRECT VACANCY RATE |
WEIGHTED NNN ASKING RATE(PSF) |
CURRENT QUARTER LEASING ACTIVITY (SF) |
YTD LEASING ACTIVITY (SF) |
CURRENT QUARTER NNN ABSORPTION (SF) |
YTD NNN ABSORPTION (SF) |
CURRENT QUARTER DELIVERIES (SF) |
% PRE-LEASED DELIVERIES |
CONSTRUCTION PIPELINE (SF) |
|---|---|---|---|---|---|---|---|---|---|---|
| NORTH | 66,091,776 | 4.7% | $0.71 | 374,830 | 374,830 | 458,877 | 458,877 | 937,034 | 0.0% | 2,532,470 |
| NORTHEAST | 24,935,913 | 10.8% | $0.62 | 476,719 | 476,719 | 355,629 | 355,629 | 150,416 | 100.0% | 1,002,017 |
| NORTHWEST | 88,700,684 | 4.8% | $0.69 | 1,623,186 | 1,623,186 | 2,712,052 | 2,712,052 | 4,273,571 | 75.8% | 3,649,424 |
| FAR WEST | 36,847,193 | 4.5% | $0.69 | 884,751 | 884,751 | 1,939,594 | 1,939,594 | 1,063,890 | 0.0% | 252,800 |
| SOUTH | 20,518,028 | 10.4% | $0.70 | 149,714 | 149,714 | 90,000 | 90,000 | 1,338,206 | 0.0% | 1,614,410 |
| SOUTHEAST | 83,265,602 | 8.9% | $0.64 | 1,855,870 | 1,855,870 | 1,330,744 | 1,330,744 | 793,648 | 16.3% | 5,123,532 |
| SOUTHWEST | 43,052,428 | 2.4% | $0.70 | 434,938 | 434,938 | 330,106 | 330,106 | 144,459 | 27.6% | 2,464,746 |
| CBD/EaDo | 4,242,890 | 8.8% | $0.55 | 53,522 | 53,522 | 41,000 | 41,000 | 0 | n/a | 0 |
| DISTRIBUTION TOTALS |
367,654,514 | 6.2% | $0.67 | 5,853,530 | 5,853,530 | 7,258,002 | 7,258,002 | 8,701,224 | 40.9% | 16,639,399 |
Outlook
Key Risks & Opportunities
- Continued port-driven demand supporting Southeast Submarket
- Potential near-term vacancy pressure in bulk product
- Moderating construction starts due to capital constraints
Houston’s industrial market is entering a phase of sustained equilibrium, with demand-driven fundamentals supporting continued stability despite elevated supply levels.
Houston’s industrial distribution market is positioned for steady performance through 2026, following a period of rapid expansion and subsequent normalization. Pricing has stabilized at a higher baseline, with the citywide weighted NNN asking rate at $0.67 per square foot, while vacancy remains within a healthy range as new deliveries continue to be absorbed.
Demand remains durable, led by logistics, distribution, manufacturing, and infrastructure-related users. The Southeast submarket, in particular, is expected to remain a primary growth engine, supported by continued expansion at Port Houston and ongoing supply chain diversification trends. This port-driven demand continues to reinforce Houston’s strategic importance within national distribution networks.
On the supply side, development pipelines remain active but increasingly disciplined. Rising construction costs, capital constraints, and a more selective financing environment are expected to moderate speculative starts, with developers prioritizing projects aligned with tenant demand and pre-leasing activity. Houston continues to benefit from broader supply chain diversification trends, as occupiers expand Gulf and East Coast distribution networks.
Looking ahead, market performance is expected to be increasingly segmented. Core submarkets with strong infrastructure access, particularly the Southeast, Northwest, and North Houston submarkets are likely to outperform, while older or less connected areas may face greater competitive pressure. Houston’s industrial market is increasingly defined by execution rather than expansion, with performance driven by location, product quality, and tenant alignment.
Overall, Houston’s industrial market is expected to deliver low single-digit rent growth, stable vacancy, and continued absorption, reinforcing its position as one of the most resilient and investable logistics markets in the U.S.
Sales Overview
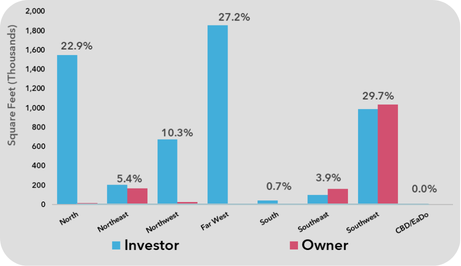
Buyer Type by Submarket
In Q1 2026, the industrial distribution market recorded 6.8 million square feet of sales activity, reflecting steady volume within a more selective capital environment. Institutional buyers led activity with 5.4 million square feet, while owner-user acquisitions totaled 1.4 million square feet, or roughly 21% of volume.
Sales were concentrated in the Southwest, Far West, and North submarkets, which collectively accounted for 80% of volume. The Far West and Southwest led activity, supported by large-scale and portfolio transactions attracting institutional and global capital due to modern inventory and strong infrastructure access.
Pricing remained stable during the quarter, with cap rates holding firm as investors targeted well-leased assets. Capital remains selective, with strongest demand for stabilized Class A product, while value-add opportunities face wider bid-ask spreads and longer marketing timelines.
Overall, Houston remains a highly competitive and liquid industrial investment market.
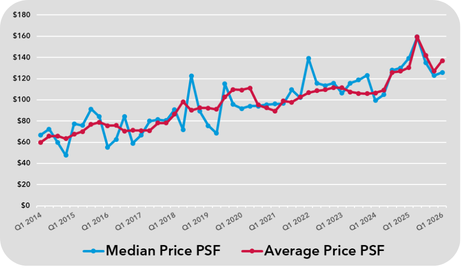
Historical Distribution Sales Price
Over the past decade, industrial distribution market has demonstrated strong price appreciation, with volatility driven by capital markets and transaction mix. Early-cycle pricing ranged between $60 and $90 per square foot from 2014 through 2018 as the market matured and institutional participation expanded.
Pricing gained momentum in 2019 and remained resilient through 2020–2021, with values holding near or above $100 per square foot despite economic uncertainty. Beginning in 2022, limited supply, rising construction costs, and cap rate compression drove pricing higher, particularly for modern, well-leased assets.
Sale prices peaked in mid-2025 at approximately $159 per square foot. Since then, pricing has moderated to $137 per square foot in Q1 2026, reflecting modest cap rate expansion.
Despite this normalization, pricing remains elevated, supported by durable tenant demand and continued investor interest in high-quality industrial assets.
Economic Update
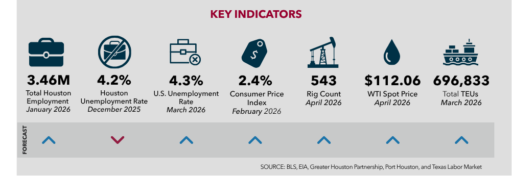
Houston’s economy remains stable, with moderating inflation and steady employment supporting continued industrial demand.
Houston’s economy remained strong during the first quarter for 2026, supported by steady job growth and resilient demand across key industries. Total employment reached approximately 3.46 million, while the unemployment rate increased modestly to 4.3%, remaining in line with historical norms and even with the U.S. rate of 4.3%. Hiring activity continues across trade, transportation, manufacturing, and professional services, reflecting ongoing population growth and business investment.
Inflation has continued to moderate, with CPI rising 2.9% year-over-year, supporting improved consumer confidence and business planning. In the energy sector, WTI crude averaged approximately $112.06 per barrel, while the U.S. rig count held steady at 548, indicating disciplined production levels.
Port Houston remains a key economic driver, handling approximately 2.9 million TEUs year-to-date and supporting strong regional logistics activity.
Overall, stable employment, moderating inflation, and consistent trade volumes continue to underpin Houston’s industrial and distribution demand heading into 2026.
Industrial Employment Growth
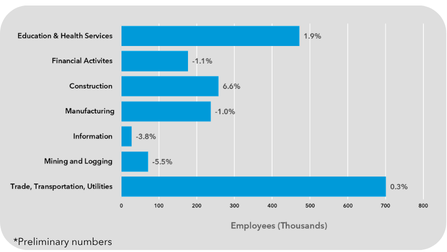
Growth By Industry
January 2026 – Year-Over-Year Change
Employment trends across construction and logistics remain supportive of industrial demand, though several sectors saw notable declines.
Houston’s labor market in January 2026 showed mixed performance, with growth led by construction activity. Construction employment rose 6.6% to 257,900 jobs, reflecting continued development momentum. Trade, Transportation, and Utilities increased slightly by 0.3% to 701,200 jobs, indicating stable—though moderating—demand for logistics and distribution.
Education and Health Services grew 1.9% to 472,300 jobs, supporting overall economic stability.
However, declines were observed across several sectors. Mining and Logging dropped 5.5%, while Information fell 3.8%, highlighting volatility in energy and tech-related industries. Manufacturing decreased 1.0%, and Financial Activities declined 1.1%.
Overall, strength in construction and logistics continues to support industrial demand, though broader softness may weigh on near-term growth.
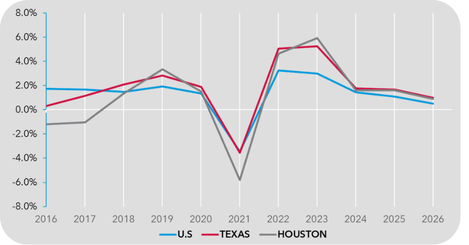
Employment Growth
January 2026 – 10 Year Change
Houston’s industrial employment growth has slowed, reflecting a shift toward more moderate, sustainable expansion.
Over the past decade, Houston’s industrial employment has generally mirrored state and national trends, though with pronounced swings linked to energy market cycles. After modest growth in the mid-2010s and declines in 2016–2017, Houston outpaced the U.S. in 2018–2019, growing 1.3% and 3.4%, respectively, supported by strong statewide and national momentum.
The pandemic triggered a sharp contraction of –5.8% in 2021, steeper than both Texas (–3.5%) and the U.S. (–3.4%), followed by a robust recovery in 2022–2023, when growth rebounded 4.6% and 5.9%, respectively.
Since 2024, growth has moderated, with Houston rising just 1.6% in 2025 and 0.9% projected for 2026, reflecting a transition from recovery-driven gains to steady, sustainable expansion supporting industrial demand.
Major U.S. Port Update
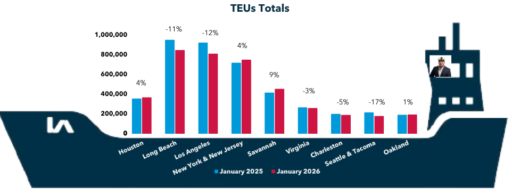
Port Houston continues to structurally gain share as Gulf and East Coast ports outperform West Coast gateways.
Major U.S. port activity in January 2026 reflected a continued shift in cargo flows, with Gulf and East Coast ports posting gains while several West Coast ports saw notable declines. Port Houston handled approximately 370,000 TEUs, representing a 4% year-over-year increase and reinforcing its steady growth trajectory.
Similarly, the Port of New York & New Jersey and Savannah recorded increases of 4% and 9%, respectively, highlighting sustained strength across eastern distribution corridors. In contrast, West Coast ports experienced declines, with Los Angeles and Long Beach down 12% and 11%, respectively, while Seattle/Tacoma fell 17%.
This divergence reflects ongoing supply chain realignment and port diversification strategies. For Houston, continued volume growth supports its role as a key logistics hub, reinforcing long-term demand drivers for industrial distribution space across the region.
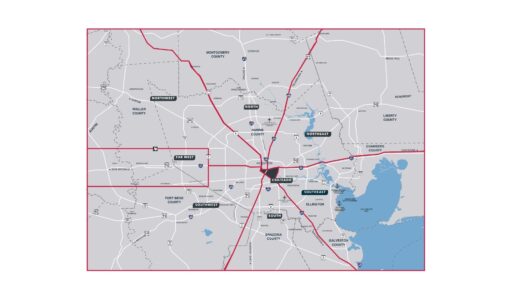
Industrial Submarket Map
Research Team
- MARY DOETTERL | RESEARCH DIRECTOR | | [email protected]
- NATHAN KRUEGER | RESEARCH ANALYST
- JASMINE HUANG | JUNIOR RESEARCH ANALYST