
Annual Interface Houston Industrial Summit Q3
CONFERENCE OVERVIEW
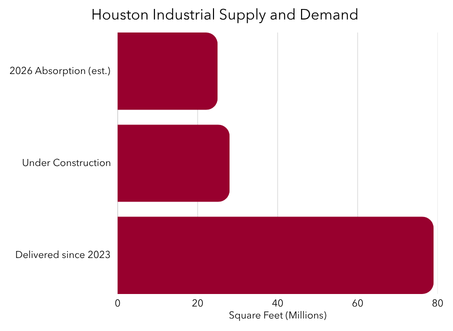
Four panels, twenty-seven speakers, and one question: How long will this demand last?
The Lee & Associates Research team attended the InterFace Houston Industrial Summit to evaluate the forces shaping the Houston industrial demand, development and investment.
Four panels covered the market end to end, from tenant and landlord representation through architecture and construction, development and ownership, and investment sales. Across the panels, several themes consistently surfaced.
FIVE MARKET SIGNALS
- AI and data center demand dominate the conversation, while advanced manufacturing emerged as the more durable industrial trend.
- Land, power and materials are increasingly constraining how quickly new product can reach the market.
- Higher construction costs are flowing through to rents and renewal economics.
- Owner-user demand is strengthening, particularly among manufacturing users making major capital investments.
- Capital remains available for quality assets, but underwriting and site selection are becoming more selective.
TENANT/LANDLORD REPRESENTATION
PANEL ONE
Renewal economics are becoming one of the market’s toughest conversations as legacy rents collide with today’s higher replacement costs.
The panel discussion centered on a rising industrial cost stack. Land prices have increased sharply over the past two years, hard costs continue to climb, and steel pricing has recently moved higher, while interest rates and cap rates were described as relatively stable. The pressure is increasingly concentrated on the cost side and flowing directly into asking rates.
Renewals are particularly difficult for tenants moving off COVID-era rents. Reported increases of 30% to 50% can be difficult for lower-margin logistics users to absorb, while advanced manufacturing tenants may have greater capacity to manage higher occupancy costs.
Manufacturing supply is also constrained. Buildings with heavy cranes, usable yards and adequate power are scarce, making off-market sourcing increasingly important. Concession discussions are becoming more focused on tenant improvement allowances as owners balance higher capital costs and tenant requirements.
40-50%
Land price increase over 2 years
12-14 mo
Transformer lead times
ARCHITECTURE AND DESIGNERS
PANEL TWO
Construction timing is becoming an increasingly important risk factor as material pricing, subcontractor availability and site constraints compress development schedules.
COST + SCHEDULE PRESSURE
Joist and deck lead times have moved, while steel pricing was reported to increase about 15% over a two-week period after an extended period of stability.
Subcontractor availability is increasingly a schedule risk. One trade partner falling behind can delay the entire project, making reliable execution more important than the lowest bid.
Developers are being encouraged to re-bid work quickly as material pricing changes.
SITE FEASIBILITY + RISK
Detention can add roughly $750,000 per acre, while drainage and access constraints can materially alter project feasibility.
Pipeline easements, MUD annexation, utility capacity and permitting requirements can add months to a development schedule.
Pending post-Harvey FEMA flood maps were identified as an important future cost and design risk for affected projects.
AI adoption is becoming practical and targeted, particularly for proposals, permitting documents, and schedule analysis.
DEVELOPERS
PANEL THREE
The developer panel described a Houston industrial market with strong demand, but a growing scarcity of development-ready land.
LAND SCARCITY IS CHANGING THE DEVELOPMENT MODEL
Clean, rectangular sites near Houston are increasingly difficult to find, pushing development farther from established corridors while land pricing remains firm.
Available sites often require extensive underwriting around pipelines, drainage, easements, floodplain and access before a project can move forward.
Infill and brownfield redevelopment only becomes competitive when existing structures are genuinely obsolete, otherwise, new speculative development struggles to compete on costs.
OWNER-USER DEMAND IS A STANDOUT
A Southwest Houston project reportedly leased or sold 1.2 million square feet of a 1.35 million-square-foot first phase within six months of delivery, with most activity attributed to owner-occupiers.
Manufacturing users making major investments in clean rooms and specialized equipment have a stronger incentive to control occupancy and avoid lease-expiration risk.
Big-box demand has also returned, with 400,000 to 800,000 square-foot transactions accounting for 29% of first half of 2026 deal volume.
KEY TAKEAWAY: Strong demand is meeting a much tighter development pipeline, making land quality and owner-user demand increasingly important to the next cycle of growth.
INVESTMENT SALES
PANEL FOUR
Capital remains selective, but investor demand for high-quality Houston industrial product remains strong.
The investment sales discussion emphasized a widening distinction between stabilized, well-leased assets and value-add opportunities that require more capital and longer hold periods.
Strong leasing and limited new supply continue to support investor interest in quality industrial properties, while higher construction and land costs are reshaping replacement economics.
Pricing is increasingly being set on an asset-by-asset basis as buyers scrutinize tenancy, credit, location, building functionality and future capital needs.
The panel discussion pointed to continued liquidity for high-quality assets, with more selective underwriting for transitional or heavily capital-intensive opportunities.
RESEARCH PERSPECTIVE: Demand is not the constraint; quality and scarcity of product are the differentiators.
85%
of delivered space leased
15%
of the pipeline if preleased
5.8
cap on a Class A credit trade
$200/SF
trades will become routine
INDUSTRIAL ADVISORS
INDUSTRIAL ADVISORS
MIKE SPEARS, SIOR,CCIM
MANAGING PRINCIPAL
MASON ALSBROOKS, SIOR, CCIM
EXECUTIVE PRINCIPAL
THOMAS LEGER,SIOR
EXECUTIVE PRINCIPAL
RICHARD GLASS, SIOR
PRINCIPAL
PATRICK WOLFORD, SIOR, CCIM
PRINCIPAL
VICE PRESIDENT
DIRECTOR
DIRECTOR
DIRECTOR
DIRECTOR
DIRECTOR
DIRECTOR
ASSOCIATE
ASSOCIATE
ASSOCIATE
PRESTON YAGGI, SIOR,CCIM
EXECUTIVE PRINCIPAL
CHASE CRIBBS, SIOR
PRINCIPAL
JUSTIN TUNNELL, SIOR
PRINCIPAL
SENIOR VICE PRESIDENT
SENIOR DIRECTOR
DIRECTOR
DIRECTOR
DIRECTOR
DIRECTOR
ASSOCIATE
ASSOCIATE
ASSOCIATE
ASSOCIATE
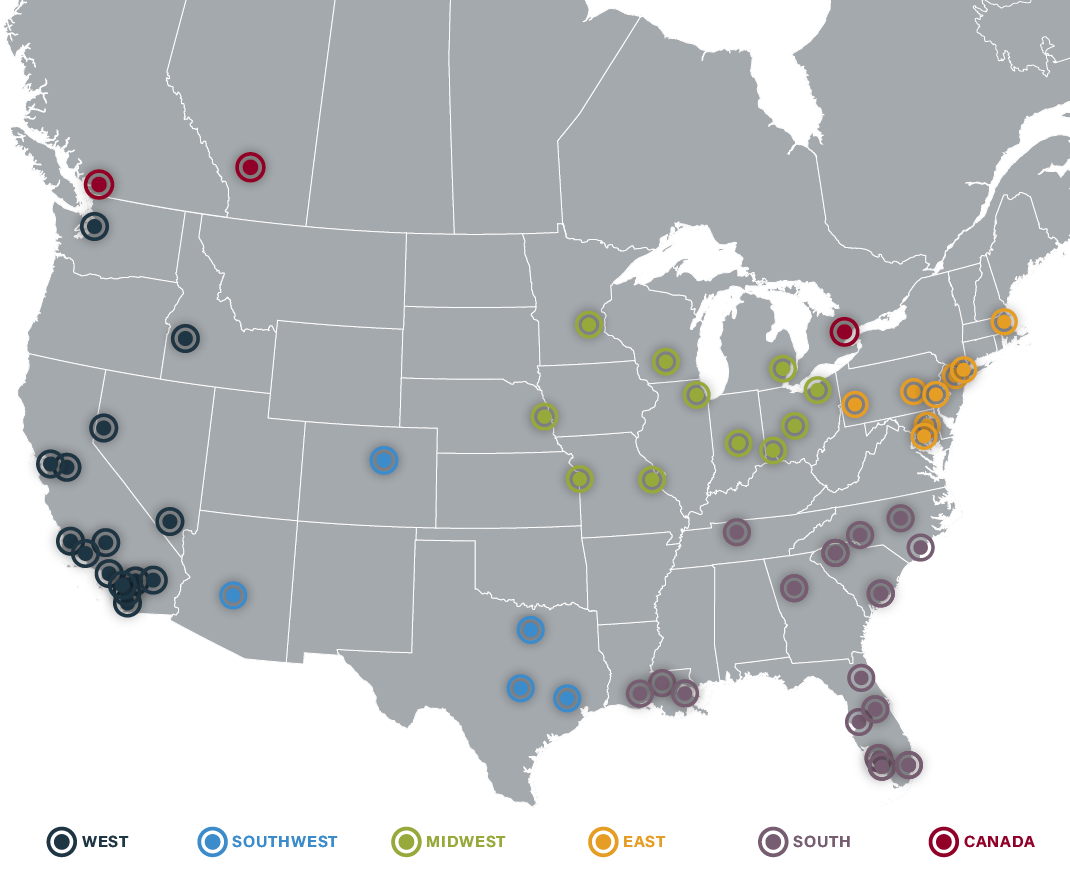
LOCAL EXPERTISE. INTERNATIONAL REACH.
With offices in 85+ markets across North America, Lee & Associates has the ability to deliver first-class services to our clients both locally and internationally.
THE LEE ADVANTAGE
Lee & Associates – Houston is a fully-integrated commercial real estate company with unrivaled market knowledge and an unwavering commitment to integrity and excellence. Our business-minded brokers specialize in office, industrial, and land real estate investments. The brokerage is uniquely qualified to support our client’s real estate needs in Houston, across Texas, and throughout the US.
RESEARCH TEAM
- MARY DOETTERL | RESEARCH DIRECTOR | [email protected]
- ELIZABETH WANG | SENIOR RESEARCH ANALYST
- NATHAN KRUEGER | RESEARCH ANALYST
- KATIE MARTINEZ | JUNIOR RESEARCH ANALYST